Bitcoin Reclaimed $73,200 — but the Market Still Doesn’t Trust the Reclaim
Bitcoin reclaimed $73,200 after the hot CPI print, but it is stuck under $74,000 and the market does not trust the reclaim: $630-720M in longs were liquidated in 24 hours, leverage rebuilt just as fast, and the December debate is priced at ~85% for 25bp versus ~15% for 50bp.
CX
CoinXSight Alpha DeskQuantitative Research Desk·Nov 11, 2026 · Updated Nov 11
Bitcoin is back above $73,200. That sentence is true, and for now it is the least interesting thing about this market. By early afternoon in Vietnam the price was sitting near $73,950 — above the line it lost overnight, below the $74,000 ceiling that has capped every bounce since, and underneath a derivatives market that spent the morning doing what it has done all week: leaning long into a falling tape and paying for it. Roughly $630–720 million in leveraged positions were liquidated in the past 24 hours, most of them longs. The reclaim happened. The trust did not come with it.
That is the position this afternoon’s market is in: not a recovery, and not a collapse either, but a standoff. The morning’s story was the shock — a hot CPI print landing exactly on the threshold a Fed governor had drawn the night before. The afternoon’s story is what traders did with the shock, and the answer is that they bought the dip, got flushed, and then, remarkably, bought it again.
The reclaim, measured
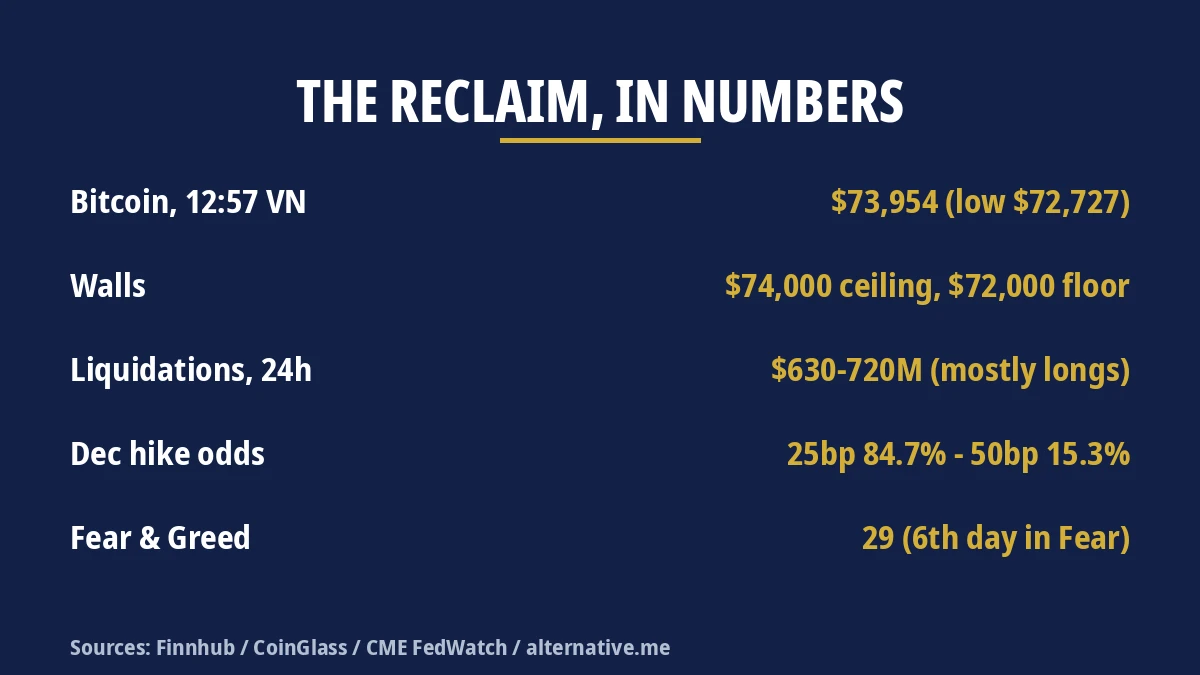
Start with the tape, because the tape is the only part of this story that is not an opinion. Bitcoin traded as low as $72,727 overnight on Binance, the weakest print since the Sunday flush, and by 05:57 UTC (12:57 VN) it was changing hands at $73,954 — up off the low by more than $1,200, still down 1.2% on the day, and still sitting below Tuesday’s close of $74,212. The day’s range so far, $72,727 to $74,996, tells the story in one line: the break happened, the reclaim happened, and neither side has won yet.
The levels around the price are unusually well defined right now, because positioning data puts walls almost exactly where the chart does. One live positioning read has the upper wall at $74,000, the lower wall at $72,000, and the flip — the line where the market’s bias changes — at $73,500. Bitcoin at $73,950 is sitting just above that flip, which is the worst place to be for anyone who wants a clean read: a few hundred dollars either way and the story changes completely. Above $74,000, the reclaim starts to look like a base. Below $73,500, it starts to look like a dead-cat bounce with a $72,000 retest attached. The next marker down if $73,200 gives way a second time is $70,000. The reclaim that would actually change the conversation — $75,500, the 50-week moving average — is about $1,550 away, and bitcoin has been capped below it ever since the weekly close below $75,000 set the tone for CPI week.
Ethereum is the weaker half of the same picture, and it is not close. ETH was trading at $2,072.50 at the same 05:57 UTC snapshot, down 2.5% in 24 hours and 9.9% on the week, with a day range of $2,006 to $2,126.51. The overnight low of $2,006 came within a whisker of the $2,000 round number, and ETH has now fallen roughly 10% in a week while bitcoin is down about 4% over the same stretch. It closed Sunday below its 200-day moving average for the first time since August 18, and it has led every leg of this sell-off down. When the market sells, it sells ETH first and asks about bitcoin later.
Sentiment has caught up with the price. The Crypto Fear & Greed Index reads 29, in Fear, down from 32 yesterday and 34 a week ago. It has now spent six consecutive days in Fear. That is not panic — panic is below 25 — but it is a market where nobody is in a hurry to be the hero, which is exactly what a reclaim without follow-through looks like from the inside.
The flush: longs paid, then re-longed
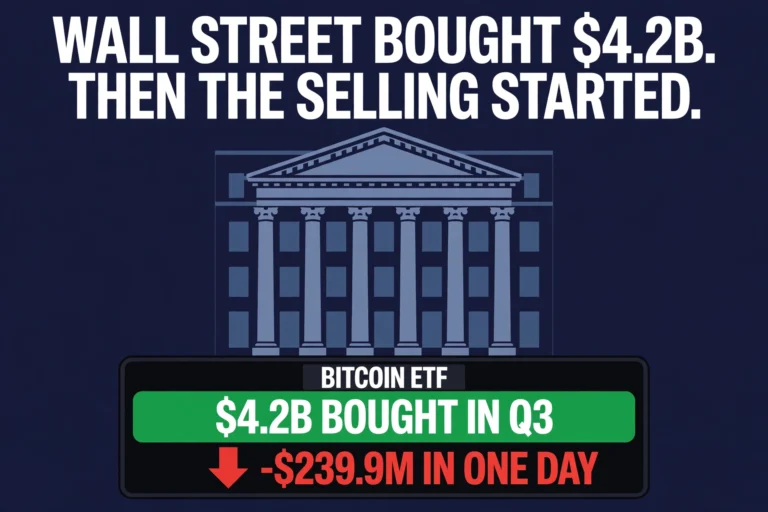
The liquidation numbers are the afternoon’s real story, because they show what the reclaim cost. Across the main trackers, roughly $630–720 million in positions were wiped out in the 24 hours after the CPI print — CoinGlass put it at $632 million through one wire, $723 million through another read of the same data, and AlphaFinance at $700 million. The trackers disagree on the total because they cover different venues and windows, so the honest way to write it is the range. What they agree on is the direction of the pain: longs took most of it, about four-fifths on the latest reads, with roughly $556–570 million in long liquidations against about $145 million in shorts. Bitcoin alone accounted for about $203 million of the total, $175 million of it longs.
Keep the scale straight. This is a real flush, and it is a new one: it belongs to Tuesday’s CPI, not to the $1.15–$1.2 billion Sunday–Monday wave, and the two should never be added together or re-dated into each other. The post-CPI wave is smaller than the Sunday wave and much larger than the quiet $277–382 million days that preceded it. The market went from complacent to flushed in one print, and the flush is what the reclaim is standing on.
Here is the part that should give a careful reader pause: the leverage did not stay down. Bitcoin perpetual funding is still sitting at the ~0.0100% per 8-hour baseline — about 10–11% annualized — which means longs are still paying shorts to hold their positions, not the other way around. Open interest across venues is roughly $30 billion, up about 2% in 24 hours rather than down. And the OKX long/short account ratio, which counts accounts rather than money, actually rose to 2.89 from 2.58 — nearly three long accounts for every short. Read together, that is not a market that got scared straight. It is a market that got flushed, then rebuilt the same bet at a slightly lower price, with the same crowd on the same side. The next flush, if one comes, has fresh fuel.
That is why the $73,500 flip matters more than the $73,200 line. A reclaim built on re-leveraged longs is a reclaim that needs the price to keep cooperating. If claims on Thursday or PPI on Friday give the tape another reason to fall, the same accounts that just re-longed are the first supply on the way down, and the $72,000 wall underneath is the only thing between the price and $70,000.
The Fed debate is now a price, not a question
On the rates side, the morning’s shock has hardened into a price, and the price has barely moved since. CME FedWatch, as cited after the print, puts a December hike at effectively certain — 0% odds of a hold — with a 25-basis-point move at about 85% and a 50-basis-point move at about 15%. The exact split depends on the snapshot: one CME-cited read had it 84.7% to 15.3%, another 85.3% to 14.7%. Polymarket’s December market reads a little cooler on the big move, roughly 84.5% for 25 basis points and about 11% for 50 or more, with a small chance of no change. The venue range is 25bp at ~84–85% and 50bp at ~11–15% — the shape is the same everywhere, even if the decimals differ. The live CME page itself would not render fresh odds in this session, so those are the latest citable reads; the point is the range, not the second decimal.
The more interesting number is further out. By January, the market now gives 50 basis points of cumulative hikes a higher probability (48.8%) than 25 (43.9%), with a 7.4% chance of 75. That is the market saying December is not the end of the story. Waller’s threshold and Logan’s “at least two more” — the two hawkish turns this morning’s recap of the hot CPI print covered in full — have been joined by a third voice from the other side, and it is worth hearing.
Robin Brooks, the former chief economist at the Institute of International Finance and ex-Goldman Sachs strategist, says the Fed will not hike 50 basis points in December despite the hot print. His argument is that the CPI surprise is, in his words, a vestige of the recent spike in oil prices — October was, he wrote, “the peak of the second big oil price shock this year,” and the run-up in oil “heavily contaminated” the report. He called the details of the report “discouraging” while arguing the contamination means the Fed should look through it. It is the only serious counter-argument in circulation right now, and it has a testable claim attached: if the oil effect fades, the next prints should cool on their own. Friday’s PPI is the first chance to check.
Deutsche Bank, meanwhile, went the other way after the print, adding a January hike to its call: 25 basis points in December, January, and March 2027, taking the policy range to 4.50–4.75%. That is three hikes, not one, and it closes the one-and-done December hike debate that framed last week. The disagreement is no longer between hikes and no hikes. It is between one hike and three, and between 25 and 50 in December — and the bond market has already voted with its feet. The 10-year Treasury touched above 5.00% after the print, the first time in 12 days, before closing Tuesday at 4.983%, up 11.9 basis points. One honest caveat for today: there will be no fresh read on yields in Wednesday’s session, because it is Veterans Day and the US bond market is closed. Stocks trade normally; bonds do not. Until Thursday, the last word on rates is Tuesday’s close.
Positioning snapshot — Wednesday midday, Vietnam time
What
Reading
What it means
BTC (Binance, ~13:00 VN)
$73,954; day range $72,727–$74,996; Tue close $74,212
Reclaimed $73,200, stuck under $74,000; flip at $73,500
ETH (Binance, ~13:00 VN)
$2,072.50; day range $2,006–$2,126.51; −2.5% 24h, −9.9% 7d
Weaker than BTC; $2,000 is the line that matters
Liquidations, 24h
~$630–720M across trackers; ~80% longs; BTC ~$203M
Post-CPI flush, not the Sun–Mon $1.15–$1.2B wave; do not merge them
Hike certain; size is the debate; Brooks says no 50bp
January cumulative
50bp 48.8% vs 25bp 43.9%; Deutsche Bank: hikes Dec, Jan, Mar
Market pricing more than one hike
Fear & Greed
29 (Fear), down from 32; six straight days in Fear
No panic, no heroics — a market waiting
What decides it next
The calendar between now and the December 8–9 meeting is thin, but the next two prints are the ones that will decide whether Brooks or Waller is right. Jobless claims land Thursday at 20:30 Vietnam time, with consensus at 195,000 against 189,000 last week — the lowest reading since 1969, which means any upside surprise lands on a labor market the Fed has already described as firming. Existing home sales follow at 22:00. Hammack and Goolsbee speak on Thursday as well, the first Fedspeak since the print that is not a rerun of Monday and Tuesday’s lines.
Friday is the bigger test. PPI arrives at 20:30 Vietnam time, forecast at +0.4% month-on-month after September’s +1.3%, and it is the second inflation print before December — the one that either confirms Brooks’s oil-contamination story or buries it. A hot PPI does to the 50-basis-point odds what Tuesday’s CPI just did. A soft one gives the 25-basis-point camp, and Brooks, their first real piece of evidence. The November CPI, the print that would restore the year-over-year comparison, does not arrive until December 10, the day after the meeting ends. The Fed will decide December without ever seeing it.
That is the shape of the week now: a market that reclaimed a level without reclaiming its nerve, a derivatives book that flushed and then re-leveraged in the same session, and a Fed debate that has moved from whether to hike to how much and how often. None of that resolves today. What resolves today is narrower and more practical: whether bitcoin can hold above the $73,500 flip into the US session, or whether the reclaim gives way and $72,000 gets its first real test since the overnight low.
The levels are the trade now, because the narrative is already priced. Above $74,000, the reclaim becomes a base and $75,500 comes back into view. Below $73,500, it becomes a bounce, and the $630–720 million flush becomes the first one rather than the last. Watch the PPI on Friday, and watch whether the longs that just rebuilt are still there when it prints. That is where the next decision gets made — and this time, unlike Tuesday, the market will have seen it coming.
Track real-time institutional orderflow, liquidity heatmaps, and whale positioning across global crypto venues with the CoinXSight Intelligence Terminal.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Figures are cited from official releases and market data as reported at the time of writing and are subject to revision. Cryptocurrency markets are volatile; always do your own research before making investment decisions.
CX
CoinXSight Alpha Desk
ALPHA // DESK
Quantitative Research Desk·Global Alpha Division
CoinXSight Institutional Research Desk produces quantitative crypto market intelligence, algorithmic models, and on-chain forensics.
QUANTITATIVE SUITE // DEEP ALPHA ENGINEACTIVE
BTC/USDT // LIVE SCANNER
CONFLUENCE 74
LIVE SPOT PRICE$82,807.47WEAK_BUY
TP2
$89,522.75
+9.07%
TP1
$85,056.42
+3.63%
ENTRY
$82,078.86
ZONE
SL
$80,590.09
-1.81%
Auto-detect Order Blocks, Fair Value Gaps and risk-adjusted DCA ladders in < 5s.