Bitcoin Slips Back Below $75,000 Into CPI — and the Market Is Now Asking Whether December Is ‘One and Done’
Bitcoin’s morning reclaim of $75,000 did not hold — it is back below the line heading into tonight’s CPI. The fresh question is no longer whether the Fed hikes in December, but whether December is ‘one and done’ after UBS projected a second hike in March 2027.
CX
CoinXSight Alpha DeskQuantitative Research Desk·Nov 10, 2026 · Updated Nov 11
Bitcoin reclaimed $75,000 on Monday night. By Tuesday lunchtime it had given the round number back — and that, more than the reclaim itself, is the story heading into tonight’s CPI report.
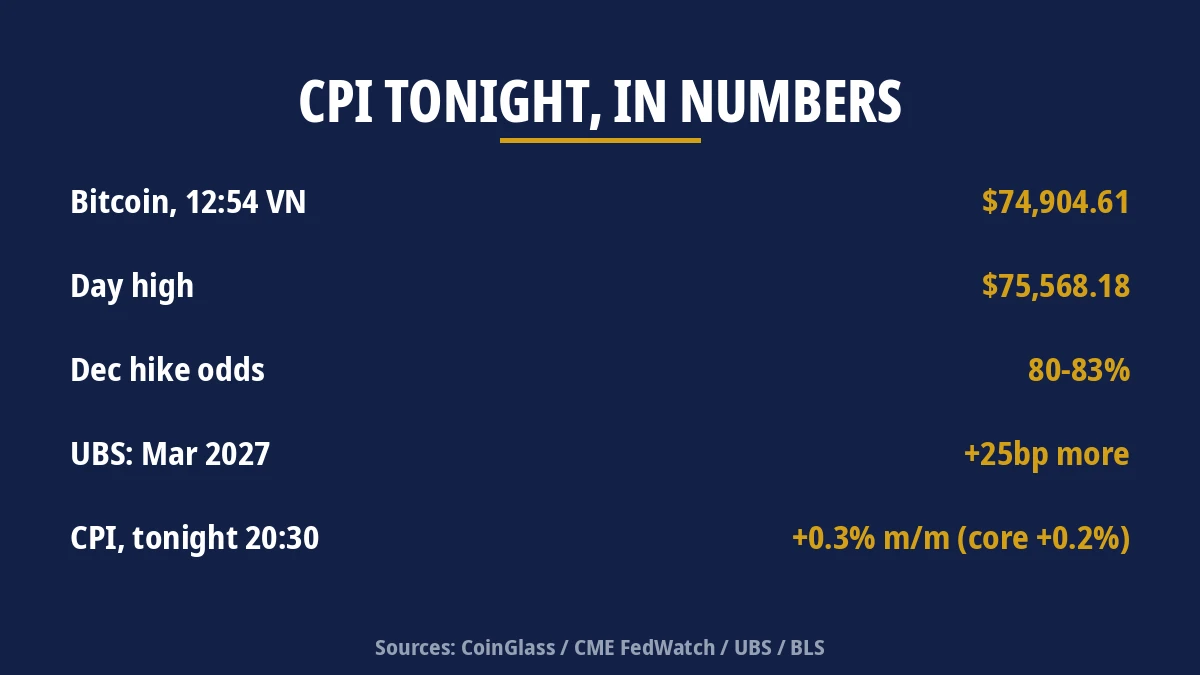
At 12:54 Vietnam time, bitcoin was changing hands at $74,904.61 on Binance, after a session high of $75,568.18 and a low of $73,750. The morning’s headline — the reclaim — was true at 07:18, when the price printed $75,212. It did not survive the morning. Ether, meanwhile, sat at $2,128.02, essentially flat against Monday’s $2,132.13 close, after a $2,083.10–$2,151.90 range.
So the market walks into the most important inflation print of the year from below the line, not above it. The $75,500 flip that capped every bounce last week is still the ceiling. The $73,200 support — and the 200-day moving average just under it — is still the floor. Nothing about the tape has changed since Monday. What has changed is the question the market is asking, and it is no longer “will the Fed hike in December?”
The reclaim that didn’t hold
Monday’s close told the story in one line: bitcoin finished the day at $74,899.67, up less than 0.1%, on a day the S&P 500 rose 2.35% to 7,549.94 — its best session since April — and the Nasdaq jumped 2.74%. Oil did the heavy lifting for equities: WTI fell 4.25% to $86.97 after President Trump said further strikes on Iran were “highly unlikely.” Crypto got none of it.
Tuesday morning briefly looked like the catch-up had arrived. Bitcoin pushed through $75,000 in the early hours and touched $75,568.18 — above the $75,500 flip for the second day running, after Monday’s intraday high of $75,599 poked through the same level. Then it faded, the same way Monday’s poke faded. Two tests, two rejections, no daily close above the level. The 50-week moving average at $75,556 sits just above the flip, so the resistance is not one line but a band, and bitcoin has now failed to close above either part of it twice in two days.
That matters because of what happened the last time bitcoin lost this ground. The weekly close was $74,737.9, down 4.5% from the $78,232 open — a fifth straight red week. Bitcoin is now more than 13% below its September high of $87,388. The Crypto Fear & Greed Index reads 32, in Fear, up a notch from 29 — a market that is less panicked than it was on Sunday night, and no more convinced.
Ether is the weaker half of the same picture. It closed Sunday below its 200-day moving average for the first time since August 18, and its Sunday low of $2,060 is still the level that matters. On Tuesday it is hovering just above $2,128, having done nothing to reclaim the ground it lost. When the market turns, ether usually leads the move in both directions. Right now it is leading nothing.
A quiet tape — and why quiet is the point
There was no new liquidation sweep on Tuesday, and that is worth saying plainly, because the numbers circulating this morning invite confusion. CoinGlass data via ChainCatcher, published at 01:43 UTC, puts total liquidations over the past 24 hours at about $277 million — $177 million in longs, $100 million in shorts. Bitcoin longs accounted for $39.66 million of it, ether longs $48.25 million. That is a quiet day by any standard of this market.
The bigger figure you may have seen — more than $1.2 billion liquidated, $1.04 billion of it longs — is real, but it is not today’s number. It is the Sunday–Monday overnight wave, repackaged under a Tuesday date by at least one outlet. That wave ran to more than $1.15 billion in total, with ether traders accounting for over $500 million against roughly $309 million for bitcoin, and about 168,000 traders liquidated. The largest single order was a $48.2 million ether long on Binance. It belongs to Sunday night, when bitcoin briefly fell to $73,500 and then rebounded above $75,400. Do not let anyone re-date it as a Tuesday event.
The quiet matters because it tells you where positioning actually sits. Nobody is being forced out today. The CoinGlass liquidation heatmap, as of 05:05 UTC, shows what is waiting on either side instead: below $70,869, about $1.668 billion in bitcoin longs would be at risk; above $78,216, about $1.324 billion in shorts. For ether, the clusters sit below $2,021 ($866 million in longs) and above $2,233 ($780 million in shorts). Those are not predictions. They are the map of where a sharp move in either direction would feed on itself — and tonight’s CPI is the kind of event that can produce one.
That is the positioning picture in one line: a market that has stopped bleeding, has not started buying, and is sitting between two liquidation clusters with a binary data release five hours away.
The question changed: is December “one and done”?
Go back a week and the debate was whether the Fed would hike at all in December. That debate is effectively over. The odds of a 25-basis-point hike at the December 8–9 meeting now sit between roughly 80% and 83% depending on the venue: 83.4% on CME FedWatch as cited by TheStreet at 00:47 UTC, 81.4% on centralbank.watch’s futures model updated at 03:14 UTC, and 80.5% on Kalshi, 79.5% on Polymarket and 81.7% futures-implied on PredictionMarketsPicks as of 12:30 a.m. Eastern. The CME’s own FedWatch page did not return a fresh reading in this morning’s checks, so the range above is the honest number — every venue agrees the hike is the base case, and no venue prices it as a certainty.
The new question, and the one this afternoon’s article exists to ask, is what comes after December. A UBS Wealth Management note published on November 9 projects a measured tightening cycle: a 25-basis-point hike in December, then another 25-basis-point hike in March 2027. If that is right, December is not the end of the story. It is the first step of a cycle, and the market has barely begun to price the second step.
That reframing is why Monday’s Fed speakers matter more than they first appeared. Chicago Fed President Austan Goolsbee called the inflation record a failure and said the AI data-center buildout is “starting to look like old-fashioned demand overheating.” Richmond Fed President Tom Barkin said the direction of policy is “relatively straightforward” — up — and that “the risk lies on the inflation side of our dual mandate.” Both men refused to commit to December, and neither framed December as the last move. This morning’s Fed recap carries their remarks in full; the point to carry into tonight is that neither official gave the market a reason to believe one hike finishes the job.
The household side of the same story has not moved either. The New York Fed’s October Survey of Consumer Expectations, released on Monday night, held one-year inflation expectations at 3.9%, three-year at 3.3% and five-year at 3.0% — all unchanged from September, all parked nearly double the Fed’s 2% target. The perceived probability that unemployment will be higher a year from now jumped to 45.3%, the highest since April 2020. Households expect prices to rise 3.9% and their earnings to grow 2.6%. That gap is the affordability squeeze, and it is the reason the Fed cannot wave the inflation problem away with one hike and a press conference.
Tonight: CPI, in three branches
October CPI lands at 20:30 Vietnam time — 8:30 a.m. Eastern — and it is the last inflation reading before the December meeting. The consensus is a 0.3% monthly rise in headline CPI, down from September’s 0.6%, and a 0.2% rise in core, down from 0.3%. Deutsche Bank expects 0.2% on both; Goldman Sachs is softer still, at 0.21% headline and 0.16% core; the Cleveland Fed’s nowcast sits at 0.24% headline and 0.21% core.
Two things to get right before the number hits. First, there will be no year-over-year CPI this month. The Bureau of Labor Statistics is not publishing 12-month figures for October 2026 because last October’s index levels were never produced during the government shutdown. Any headline quoting a “3.7%” or “3.9%” annual rate is a model estimate — the Cleveland Fed’s nowcast is about 3.74% — not a BLS print. This article, and the recap that follows it, will write month-on-month only.
Second, the branches are genuinely two-sided, and the market’s positioning makes both of them live:
Core CPI tonight (m/m)
What it means
December hike odds
Bitcoin read
0.1% (soft)
Downside surprise; disinflation resumes
Ease from ~80–83%
Real reclaim case toward $75,500 and the 50-week average; a daily close above the flip would be the first sign sellers have lost the level
0.2% (in line)
Consensus delivered; nothing changes
Hold ~80–83%
Stays pinned below the flip into the print and after it; $73,200 and the 200-day average remain the floor
0.3% or hotter
Confirms what is already priced — and the UBS “not one and done” case strengthens
Hold or rise; March 2027 gets priced in
Pinned below the flip, with $73,200 as the next test; a daily close below $73,000 risks momentum selling toward $70,000
The third branch is the one to watch most closely, because it is the one the market has not fully priced. A hot core print does not just confirm December. It validates the UBS view that March follows, and it forces the market to ask whether the tightening cycle runs further than two hikes. That is a different conversation from the one that has dominated this week, and it is the conversation that would put the $73,200 support under real pressure.
On the downside, the warning is equally specific. Analysts at BRN told CoinDesk that a daily close below $73,000 could trigger momentum-driven selling toward $70,000, with a deeper move possible toward July’s lows below $60,000. That is not a prediction. It is the level where the technical picture changes from “range-bound” to “breakdown,” and it sits barely 2.5% below where bitcoin is trading now.
What the print can’t do on its own
Here is the uncomfortable part, and it is the reason this article is not a simple “soft CPI equals rally” story. Even a soft print may not be enough. CoinDesk’s overnight analysis put it plainly: a softer inflation report could spark a relief rally, but analysts said a sustained recovery would require stronger buying demand and renewed inflows into spot bitcoin exchange-traded funds. The demand source many bulls counted on to sustain the rally into year-end has faltered. Spot bitcoin ETFs saw about $1.28 billion in net outflows last week, the worst since late June, according to Bitfinex Alpha.
That is the divergence the morning article flagged and the afternoon has to sit with. Monday was the best day for US stocks since April, and crypto barely participated. Bitcoin finished the day up less than 0.1%. The equity rally was an oil trade — WTI down 4.25% on easing Iran tensions — and crypto does not trade oil. But the deeper truth is that crypto’s own demand engine, the ETF bid, has gone quiet at exactly the moment the macro backdrop turned hawkish. A soft CPI can change the rate outlook in an afternoon. It cannot manufacture ETF inflows, and without them, any relief rally is a bounce inside a downtrend rather than the start of a recovery.
The same logic applies to the “one and done” question. If December is the first hike of a cycle rather than the last, the rate outlook stays tight into 2027, and the ETF bid stays hostage to a macro regime that is getting worse for risk assets, not better. The market’s job tonight is not just to read the CPI number. It is to read whether the number gives the Fed a reason to stop — and right now, with households expecting 3.9% inflation and the Fed’s own officials calling the record a failure, the honest answer is that one soft print probably does not.
After the print
The recap lands in Wednesday morning’s slot, and it will have one unusual feature: there will be no yield read-through to hide behind. Wednesday is Veterans Day. Stocks open on normal hours, but the bond market is closed, so the 10-year Treasury — near 4.86% on Monday — will not move. The price action in bitcoin and ether will have to speak for itself, without a bond-market alibi.
The rest of the week keeps the data coming. Producer prices land on Friday at 20:30 Vietnam time, with a 0.4% monthly headline forecast against a 1.3% prior print. The minutes from the Fed’s October meeting arrive on November 18, and the PCE report — the Fed’s preferred inflation gauge — follows on November 25. Tonight is also an AI-economics test: CoreWeave reports third-quarter earnings at 5 p.m. Eastern, hours after CPI, putting the economics of the AI buildout that Goolsbee and Barkin both flagged into the same evening as the inflation data.
None of that changes what tonight is. It is a binary print, five hours away, with bitcoin sitting below the level it needs to reclaim and above the level it cannot afford to lose. The morning’s reclaim did not hold. The question now is whether the afternoon’s positioning — quiet liquidations, a Fear & Greed reading of 32, a market waiting between two liquidation clusters — survives the number, or whether the number finally picks a direction.
Know your levels before the print, not after it. The recap — with the actual CPI, the first reactions, and whether the flip finally gave way — lands in Wednesday morning’s slot.
Track real-time institutional orderflow, liquidity heatmaps, and whale positioning across global crypto venues with the CoinXSight Intelligence Terminal.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Figures are cited from official releases and market data as reported at the time of writing and are subject to revision. Cryptocurrency markets are volatile; always do your own research before making investment decisions.
CX
CoinXSight Alpha Desk
ALPHA // DESK
Quantitative Research Desk·Global Alpha Division
CoinXSight Institutional Research Desk produces quantitative crypto market intelligence, algorithmic models, and on-chain forensics.
QUANTITATIVE SUITE // DEEP ALPHA ENGINEACTIVE
BTC/USDT // LIVE SCANNER
CONFLUENCE 74
LIVE SPOT PRICE$82,807.47WEAK_BUY
TP2
$89,522.75
+9.07%
TP1
$85,056.42
+3.63%
ENTRY
$82,078.86
ZONE
SL
$80,590.09
-1.81%
Auto-detect Order Blocks, Fair Value Gaps and risk-adjusted DCA ladders in < 5s.